

UNest: Invest & Save for Kids
UNest Holdings, Inc.
- 3.8
- 430.00 Reviews
- 100.00K
- Downloads
- Free
- Price
Screenshots
UNest: Invest & Save for Kids Pros and Cons
Pros
- Automates recurring contributions, making consistent saving easier for families.
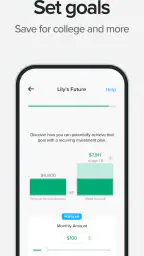
- Offers goal-based investing designed around a child’s future milestones.
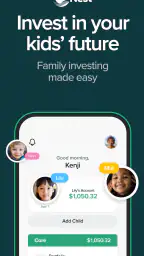
- Parents can manage multiple children’s accounts from one dashboard.
- Provides a simple mobile experience for users with limited investing knowledge.
- May support tax-advantaged custodial account options, depending on eligibility.
Cons
- Investment returns are not guaranteed and account values can fall with the market.
- Fees may reduce long-term growth, so pricing should be reviewed carefully.
- Withdrawals and account use can be subject to custodial account rules.
- Availability and features may vary by state and the child’s eligibility.
- Parents may have limited control once funds are legally designated for the child.
 Analysis by All-app
Saving for a child can sound simple until it becomes one more task competing with bills, school messages, and everyday errands. UNest: Invest & Save for Kids takes a focused approach: it is a finance app from UNest Holdings, Inc. built around a UTMA custodial account, with the aim of helping adults put money aside and invest it for a child. I found the appeal easy to understand during the first few sessions, but the more important question is whether it remains useful once the initial enthusiasm has passed.
That distinction matters with a savings app. A polished first impression is not enough if checking in feels confusing, contributions become difficult to remember, or the account does not fit the family’s actual plans. My overall view is that this is most interesting for a parent or relative who wants a child-focused investing destination rather than another general-purpose banking tool. It is less convincing for someone who wants complete control over investments, a simple cash savings account, or a hands-off product with no recurring cost considerations.
What the first week feels like
The strongest part of the experience is the clarity of its purpose. Instead of presenting itself as a broad personal-finance dashboard, the app keeps the child’s future at the center. That focus can make the first conversation about saving more concrete: the account is connected to a specific young person and a long-term intention, rather than being an abstract balance hidden among everyday spending accounts.
For a new user, the key decision is not simply whether to download it. It is whether a UTMA custodial account matches the way the family wants to give money. A custodial structure is designed for assets held for a minor, so it should be treated as a meaningful financial arrangement rather than a temporary envelope for spare cash. I would read the account terms carefully before adding money, especially if several relatives expect to contribute or if the family has a precise plan for future education expenses.
The app is free to download, which removes an obvious barrier to trying it. It also includes in-app purchases ranging from around five dollars to around one hundred fifty dollars per item, so I would not assume that every part of the experience is cost-free simply because the initial download is free. Before committing to a regular contribution, I would check the current pricing and account terms inside the app and decide whether the ongoing value justifies them.
That is one of my first practical recommendations: do not begin with an ambitious amount. Start with a contribution that can survive an expensive month, then increase it only after the habit feels stable. The usefulness of a child investment account comes from consistency and time, not from making one large deposit during the first week and forgetting about it afterward.
The app’s store rating sits at about 3.8 from roughly 2,500 ratings, and it has passed 100,000 installs. Those figures suggest that the concept has reached a meaningful audience while also leaving room for mixed experiences. I would interpret that as a reason to test the setup carefully rather than as a verdict either for or against the product. Finance apps deserve a slower evaluation than entertainment apps because mistakes can affect real money and long-term expectations.
More Reads From Our News Desk

Switching to the Xbox App: What Changes in Your Gaming Routine

Coloring & Learn Review: A Satisfying Canvas, Cluttered Menus

Microsoft 365 Copilot on Your Phone: Who Actually Needs It?

Mafia City: The Crime Saga That Outshines Its Rivals

Woodturning Transformed: How OS Updates Enhance Your Craft

How Tiles Hop EDM Rush Redefines Music Gaming
The Everyone content rating makes the app broadly accessible from an age-classification perspective, but the financial decisions still belong with the responsible adult. A child may be the reason for the account, yet the adult needs to understand ownership, control, contribution expectations, and the eventual role of the funds. That distinction is easy to overlook when the app’s language makes the process feel friendly and family-oriented.
A useful setup for family gifts
One scenario where I can see real value is a family that receives repeated cash gifts for a child. Instead of allowing each birthday or holiday payment to disappear into ordinary spending, the adults can use a dedicated child-focused account as the default destination. The important workflow is not merely depositing money; it is agreeing in advance what counts as a contribution, who is responsible for adding it, and how relatives will be told that investing is preferred over another toy.
This can also help grandparents or other relatives participate without asking them to understand the entire investing process. However, I would keep the arrangement simple. If every family member creates a different promise or expects a different future use, the account can become a source of confusion. A single adult should maintain the record of contributions and explain the purpose in plain language.
Another non-obvious benefit is conversational. A child-focused account can give parents a natural way to explain that money may be used for a future goal instead of being spent immediately. That does not turn the app into a complete financial education course, but it can support a recurring family habit: checking progress occasionally, discussing patience, and connecting saving with a real person’s future.
Where the first impression can mislead
The friendly framing should not be mistaken for a guaranteed outcome. Investing involves uncertainty, and a custodial account is not the same thing as a protected cash jar. I would avoid presenting the balance to a child as a promised amount. A better explanation is that the family is putting money to work for the future and that the value can change along the way.
This is also not the ideal first choice for an experienced investor who wants to select individual securities, build a detailed allocation, or manage several account types from one place. The narrow focus is an advantage for families who want simplicity, but it can feel restrictive to users who already have a clear investing strategy. A standard brokerage account or another dedicated education-savings option may be a better comparison, depending on the intended use of the money and the level of control required.
Why the app may still matter after the novelty fades
The month-to-month value depends almost entirely on whether the app helps a family maintain a repeatable behavior. There is no lasting benefit in opening an account and then leaving it untouched. I would judge the product less by how exciting the first deposit feels and more by whether it makes the next contribution easy to remember, easy to understand, and emotionally connected to the child’s future.
For that reason, I would pair the app with an external routine. A monthly calendar reminder, a review after payday, or a contribution connected to a recurring family event can be more important than any individual screen. The app can serve as the destination, but the habit needs a trigger outside the app. This is a useful trade-off to recognize: a specialized product may make the goal clearer, yet it cannot create discipline for a household that has no regular process.
I also recommend separating contribution decisions from market reactions. If the balance changes and the first response is to open the app repeatedly or stop contributing, the account may become a source of anxiety. A calmer approach is to decide the intended contribution schedule in advance and review the plan at sensible intervals. The app is more useful as a long-term container than as a place for constant checking.
Families should also decide what the money is for before the balance becomes emotionally significant. “For the child” is a warm intention, but it is not a complete plan. Is the money meant to support education, a first car, a future move, or general adult expenses? A UTMA custodial account can introduce obligations and expectations that are different from an ordinary savings account. Writing down the family’s intention can prevent disagreements later, particularly when the person making deposits is not the same person managing the account.
That planning step is one of the app’s hidden trade-offs. The product can make investing for a child feel approachable, but approachability may encourage users to skip the harder questions. I would use the simple interface as an invitation to plan, not as a substitute for planning. Before setting a recurring amount, I would review the account structure, tax implications, control arrangements, and how the funds may affect the child’s future situation with a qualified professional when those issues are important.
Keeping the account useful without over-managing it
A practical monthly review can be brief. I would check whether the intended contribution occurred, confirm that the account still reflects the correct child and responsible adult, and note any changes in the family’s financial situation. I would not turn that review into a daily market ritual. The goal is to catch administrative problems while preserving the long-term mindset that makes investing appropriate for this use case.
It is also worth keeping a simple private record of deposits and family gifts. Even when an app displays the account history, a separate note can help explain why money was added and who contributed it. This becomes especially useful when several relatives participate or when the account will be discussed years later. The record does not need to be complicated; the point is to reduce ambiguity.
For households with irregular income, a fixed contribution may create unnecessary pressure. In that case, a smaller baseline with occasional additional deposits can be more sustainable than choosing an amount that only works during good months. The best amount is the one the family can maintain without raiding emergency savings or carrying expensive debt. A child investment account should complement financial stability, not compete with it.
The maintenance burden is modest, but real
UNest is currently listed as version 3.8.1 and supports Android 7.0 or later. That makes compatibility fairly broad for many Android users, although the experience can still depend on the phone, operating system condition, and account setup. I would update the app when prompted, use a secure device, and avoid treating a finance app like a casual utility that can be installed and forgotten.
The main maintenance burden is behavioral rather than technical. Someone has to remember contributions, keep contact and family details current, review statements or account information, and make sure the account still fits the family’s intentions. If the responsible adult changes banks, moves, or reorganizes household finances, the child account should be included in that review rather than left behind.
There is also a mental maintenance cost. A dedicated account can create a reassuring sense of progress, but that feeling may lead to overconfidence. I would periodically ask whether the contribution remains affordable, whether the account’s purpose is still appropriate, and whether another financial priority has become more urgent. The app earns its place when it supports a healthy plan, not when it becomes a badge of being financially organized.
Compared with a normal savings account, the app’s investment orientation offers more long-term potential but less certainty and potentially more emotional fluctuation. Compared with a general brokerage app, its child-centered purpose may reduce decision overload but also limits the appeal for users wanting broad portfolio control. Compared with a dedicated education account, it may be more flexible for a general future gift, while an education-specific product may be more suitable when schooling is the clear objective. The right alternative depends on the goal, not on which app has the most attractive first screen.
What can cause fatigue over time
The first source of fatigue is repetition without visible progress. If contributions are small and market values move unpredictably, the account may not deliver the satisfying feedback that a spending tracker provides. Parents who need immediate motivation may prefer a straightforward savings method with a stable visible balance. I would choose the investment route only if I could accept that the short-term picture may be uneven.
The second is family coordination. A single parent managing the account may find it straightforward, while a household expecting several people to contribute may need more communication than anticipated. The app does not remove the need to decide who deposits money and how gifts are handled. Without that agreement, the account can become another shared responsibility that nobody fully owns.
The third is fee sensitivity. Because the download is free but in-app purchases are listed, I would examine the exact cost structure before making the product part of a long-term routine. A recurring charge can matter more than it first appears when contributions are modest. The right question is not whether a fee is automatically bad, but whether the convenience, focus, and account structure provide enough value compared with a lower-cost alternative.
The fourth is changing family circumstances. A child’s needs, the adults’ income, and the intended use of the funds can all change. A product that felt perfectly suited when the child was young may be less suitable later if the family wants different control, a different tax treatment, or a more specific education strategy. I would schedule an annual review rather than assuming the original choice remains correct forever.
There is also a risk of confusing activity with progress. Opening the app often, reading updates, or discussing the account can feel productive even when the contribution plan is not affordable or the broader household budget is under strain. My advice is to measure success by sustainable deposits and clear family expectations, not by how frequently the app is opened.
Who should use it, and who should look elsewhere
I think this app is a good fit for a parent, guardian, or relative who wants a dedicated place to invest for a child and values a focused experience over extensive customization. It is especially appealing when the family wants to turn occasional gifts into a long-term habit and is comfortable learning what a custodial account involves.
I would be more cautious if the household has high-interest debt, no emergency reserve, or an unstable budget. In those situations, directing every spare dollar toward a child account may feel generous but could weaken the family’s immediate security. I would also look elsewhere if the main goal is a guaranteed cash balance, detailed self-directed investing, or a narrowly defined education strategy that calls for a specialized account.
Before installing, I would ask myself four practical questions. Can I contribute without compromising essentials? Do I understand who controls the account and what the funds are intended to support? Am I comfortable with investment values changing? Will I actually maintain a monthly routine? If the answer to the last question is no, the app may become an attractive but inactive symbol of good intentions.
My long-term verdict
After the first-week appeal wears off, UNest: Invest & Save for Kids earns its space when it gives a family a clear destination and a repeatable reason to save. Its strongest quality is focus: the child is not an afterthought inside a broad finance dashboard. That makes the product easier to explain and potentially easier to connect with family gifts and long-term conversations about money.
Its limitations are equally important. This is not a replacement for financial planning, a guarantee of growth, or a universal answer for education funding. The custodial structure deserves careful thought, investment risk can make the balance uncomfortable to watch, and listed in-app purchase prices mean I would inspect the current cost before committing. The free download is a useful starting point, not the complete affordability story.
My recommendation is measured but positive. If you want a child-specific investing app, have a stable contribution plan, and are willing to review the account rather than abandon it after setup, this is worth considering. Start small, define the purpose, establish a reminder, and explain the arrangement clearly to anyone who contributes. If you need cash certainty, advanced investment control, or a product designed solely around education expenses, choose an alternative built for that priority instead.
In the end, the app’s lasting value comes from the habit surrounding it. UNest can make that habit more visible and personal, but the family still supplies the consistency. Used with realistic expectations, it is a focused tool for building a child’s financial start; used as a one-time download with no follow-through, its novelty is likely to fade quickly.
Frequently Asked Questions
What is UNest: Invest & Save for Kids?
UNest is a family-focused investing and savings app designed to help parents and relatives build money for a child’s future. It generally allows users to open and manage a custodial investment account, make recurring or one-time contributions, and track progress from a mobile device. Before downloading, review the current account structure, eligibility requirements, available investments, and supported state rules.
How does investing through UNest work?
After creating an account and providing the required personal and financial information, the account owner can fund the child’s investment account through scheduled deposits, individual contributions, or gifts from other people. Contributions are invested according to the options and risk settings available in the app. Investment values can rise or fall, so UNest should not be treated as a guaranteed savings account.
Is UNest safe, and is the money guaranteed?
UNest uses standard security measures intended to protect account information and transactions, but no online service can eliminate every security risk. Investments are also subject to market fluctuations and may lose value. Users should distinguish between account security and investment protection, read the app’s disclosures carefully, and confirm whether any applicable brokerage or regulatory protections cover their specific account.
What fees does UNest charge?
The cost of using UNest can depend on the account type, subscription or management model, promotional terms, and other services available when you sign up. Fees may affect long-term returns, particularly when contributions are small or the account is held for many years. Check the latest pricing page and account agreement for management fees, subscription charges, transfer costs, and any other applicable expenses.
Who can use UNest, and what happens to the money later?
UNest is primarily intended for parents, guardians, and family members saving or investing for children, but eligibility may depend on location, age, citizenship, and custodial-account requirements. The adult generally manages the account while the child is a minor. When the child reaches the legally applicable transfer age, control may pass to them, so families should understand the relevant state rules and possible tax or financial-aid implications before contributing.


